Life & Health Insurance Underwriting Case Agent
by Druid AI
Summary
Takes a life insurance application from first customer conversation to a decision-ready, fully evidenced case, verifying identity, running the medical questionnaire, validating medical evidence, and assembling a reasoned risk brief for every referred case. The agent never decides: a licensed underwriter makes every call. Engine-agnostic and policy-admin-agnostic by design, it plugs into the carrier's existing stack rather than replacing it.
Description
Life carriers have largely automated the easy applications. In many markets 75–90% now clear straight-through. The remaining referred cases are where human effort, cost, and cycle time concentrate: complex medical or financial risk that the automated engine cannot resolve alone. Underwriters spend most of their time not deciding, but hunting and gathering, chasing requirements, reading dense medical records, and documenting. That referred lane, not the straight-through lane, is where this agent creates its value.
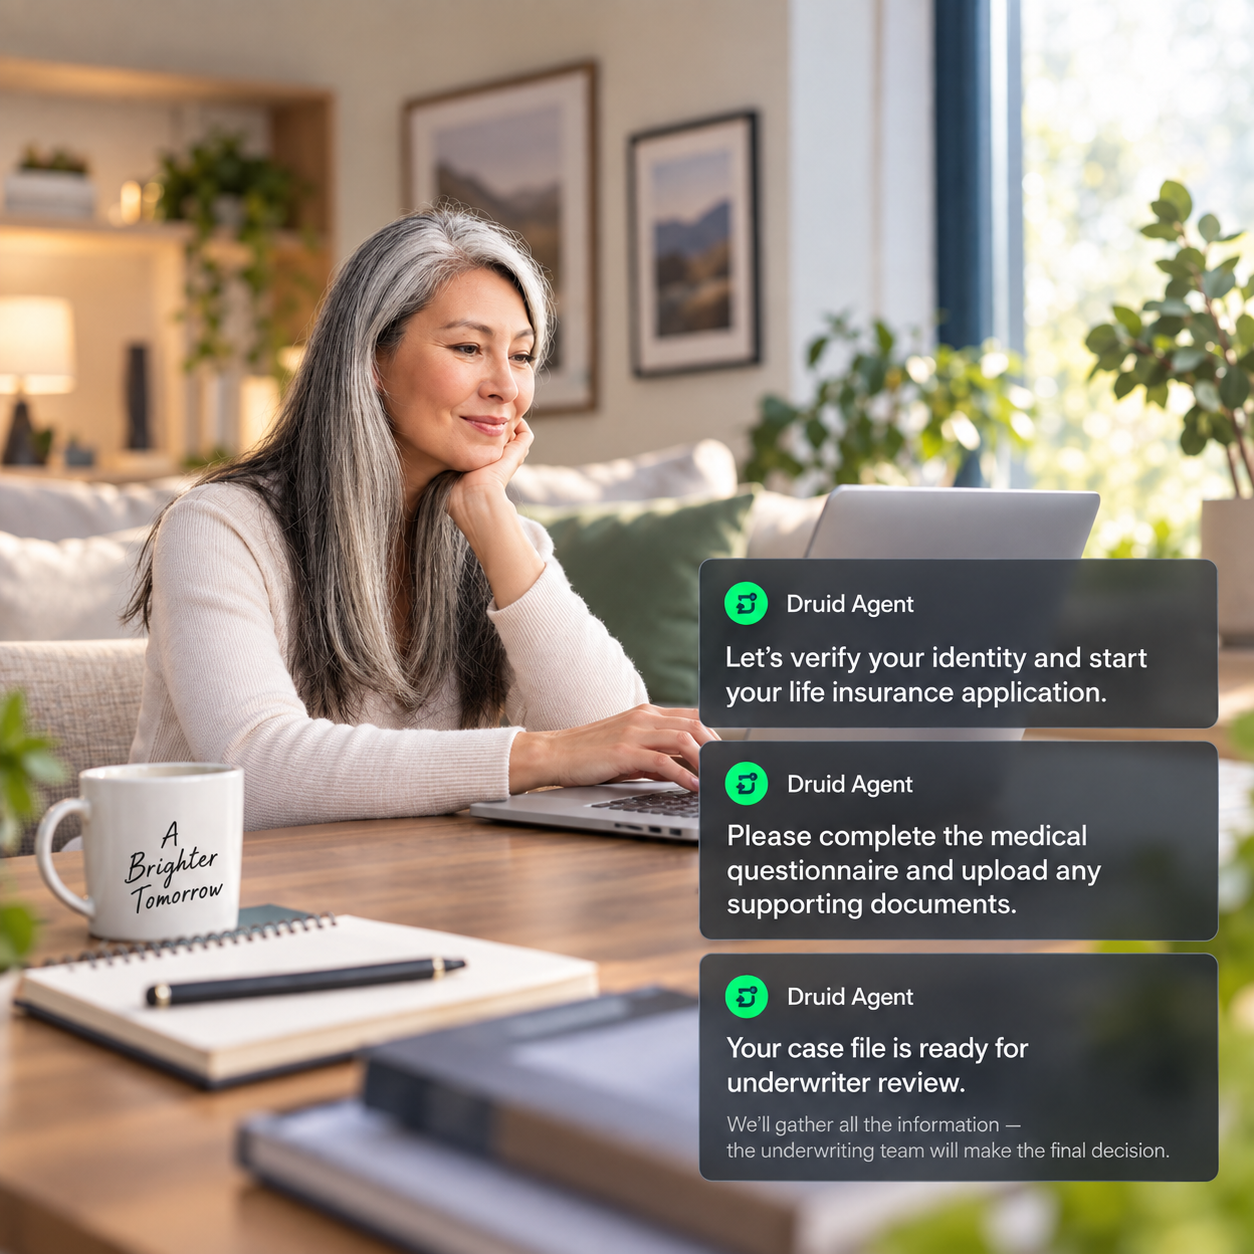
The Life Underwriting Case Agent runs the full front-of-house journey in one continuous, conversational flow: a two-layer consent capture (data protection, then specific medical-information consent) before any underwriting question is asked; automated identity verification from an uploaded ID document; a six-section medical questionnaire that adapts its follow-up questions to each answer; and medical-evidence intake with an AI-generated plain-language summary, automatic freshness validation, and a self-service path to correct an outdated report without a case handler ever getting involved.
From there, it hands the case to the underwriting team as a structured, evidenced file not a transcript to interpret. A live risk assessment (risk level, referral reasons, recommended next steps) is available on demand, the underwriter can request further evidence or issue instructions in plain language from within the same workspace, and the case re-assesses itself automatically the moment new evidence arrives. On approval, the agent generates and delivers the policy and contract for signature in the same conversation with a complete, timestamped, append-only audit trail behind every step from first consent to final instruction.
The agent is engine-agnostic and policy-admin-agnostic: it sits across the carrier's own eApp, underwriting workbench, and whichever reinsurer engine they run, rather than competing with reinsurer-owned copilots (Swiss Re, Munich Re, RGA) or replacing the workflow the way a P&C-rooted independent decisioning agent would. It ships with reference configurations for the US (enrichment-rich: MIB, Rx, MVR, EHR) and the UK (disclosure-led, centred on the electronic GP report via iGPR), built on the same core with swappable adapters. One product, two configurations, extensible to further markets.
Features
- Consent, built in first. Two-layer consent capture — data-protection consent, then specific medical-information/evidence-source consent, with the applicant's right to review the medical report before it is sent disclosed up front, all recorded before any underwriting question is asked
- KYC identity verification. Automated identity verification from an uploaded ID document — name, date of birth, address, and document details extracted and confirmed in seconds
- Graceful pause & resume. If an applicant needs to stop partway through, everything gathered so far is captured and saved rather than lost, so the case can pick up later without starting over
- Full medical questionnaire. A conversational six-section medical questionnaire — physical measurements; tobacco, alcohol & substance use; medical history; current medications; hospitalizations & surgeries; lifestyle & travel — asked one question at a time
- Reflexive follow-up logic. A disclosed condition opens the relevant follow-up questions; a clean answer closes that line immediately — the same depth asked of every applicant, in the same order
- Instant structured case record. The completed questionnaire is committed into a structured case record the instant it finishes — before the medical-evidence step even begins, with nothing left for a human to key in by hand
- AI medical-evidence summary. Test-by-test, plain-language summary of uploaded results — abnormal and normal findings and an overall read, without raw lab tables or reference ranges
- Privacy-by-design evidence handling. Only the plain-language summary is ever stored in the case file — raw OCR text, lab tables, and document formatting from the uploaded report are never persisted
- Automatic evidence freshness check. Flags results past the carrier's validity window (e.g. 3 months) with a self-service re-upload or appointment-booking path — no case manager required
- GP-record fallback integration. Retrieves supplementary medical history directly from the applicant's GP record (iGPR in the UK, or the region's equivalent), reducing follow-up requests later in the process
- On-demand automated risk assessment. Risk level, the specific reasons a case was referred, and recommended next steps, generated on demand from the assembled evidence
- Underwriter copilot chat. A copilot chat inside the underwriting workspace to request more evidence, get a live risk re-read, or issue the next instruction in plain language
- Automatic case re-assessment. The case re-assesses itself the moment new evidence lands — no manual re-open required
- Case-queue segmentation. Operational visibility across the case queue (e.g. All / Approved / Incomplete / Follow-up Documents Needed / Pending)
- One-instruction policy issuance. Policy and contract generated and delivered for e-signature in the same conversation the underwriter is already working in, on a single instruction
- Full decision audit trail. A complete, append-only, timestamped record across every step — consent, identity verification, questionnaire completion, evidence review, and the final instruction to issue
- Engine- and policy-admin-agnostic. Swappable adapters per external system, so the agent fits the carrier's existing stack instead of requiring a rip-and-replace
ROI & Benefits
- Cycle time: ≈30% reduction in referred-case cycle time (pilot target)
- Underwriter capacity: +25% cases processed per underwriter per day (pilot target)
- No-touch clearance: 60% of requirements cleared with no human touch
- Summary acceptance: 80% underwriter acceptance rate of agent-drafted summaries
- Addressable segment: Targets the 25–50% of applications that are referred — the segment where cost and cycle time concentrate, against a market where 75–90% already clears straight-through
- Governance guardrails: 100% audit-trail completeness and zero unauthorized data pulls, tracked as pilot guardrails alongside the outcome metrics above
- A licensed underwriter decides every case — the assist-first design satisfies human-in-the-loop expectations under frameworks such as GDPR Article 22 and the US NAIC Model Bulletin on AI
- Standardized, consistent questioning for every applicant — reduces the fair-treatment / conduct-risk exposure of inconsistent manual underwriting
- Protects risk-selection integrity by catching stale or expired medical evidence before it reaches a decision, rather than after
- Frees underwriter time from chasing documents to actual risk judgment — the work only a licensed underwriter can do
- Reduces application abandonment: evidence gaps are resolved in the same conversation, not an email chain, and an applicant who has to step away mid-questionnaire doesn't lose progress or have to restart
- Improves applicant experience — plain-language summaries, self-service correction, no separate portal or login
- Data minimization by design — only the AI-generated summary of medical evidence is stored, never the raw report, OCR text, or lab tables,reducing the sensitive data the carrier has to hold and protect
- Fits the carrier's existing systems — lower adoption risk and IT lift than a rip-and-replace decisioning platform
- Fully explainable and auditable for regulators, internal compliance, and reinsurer due diligence
Prerequisites
- A DRUID tenant/workspace with the Life Underwriting solution configured, and Studio access for the underwriting team
- The carrier's underwriting guidelines and risk rules encoded in the agent's configuration (referral thresholds, rating tables)
- KYC / identity-document verification enabled (OCR-based extraction)
- A defined data-protection and medical-information consent flow aligned to local regulation (e.g. GDPR; the Access to Medical Reports Act 1988 in the UK)
- Access to a medical-history / GP-record retrieval service for the target region (e.g. iGPR in the UK) or the region's equivalent enrichment sources (e.g. MIB, Rx, MVR, EHR in the US)
- A defined medical-evidence intake channel (document upload) and the underwriting team's evidence-freshness policy (e.g. a 3-month validity window)
- An underwriting team ready to work referred cases inside the platform's case queue and act on the agent's drafted briefs
- E-signature capability enabled, if using the policy/contract issuance step
- Carrier-supplied branding, legal, and policy text (privacy notice, consent wording, policy and contract templates)
Integrations
KYC / OCR identity-document verificationiGPR (UK electronic GP report retrieval) — reference integration; equivalent regional medical-record services supported via the same adapter patternMedical-evidence document intake and analysisEmail / notification system for automated applicant outreach (e.g. requesting additional evidence)E-signature, for policy and contract deliveryPolicy Administration System (PAS) — engine-agnostic adapter; no rip-and-replaceAutomated Underwriting (AUW) rules engine — engine-agnostic, compatible with reinsurer engines (e.g. Swiss Re Magnum, Munich Re ALLFINANZ, RGA AURA) or the carrier's ownCRM and enterprise systems via DRUID's standard REST/SOAP and enterprise connector layerDruid Conductor, for orchestration across the systems above
Services
- Discovery & scoping workshop — identify the 2–3 highest-volume referral reasons to target first
- Configuration of underwriting guidelines, consent flows, and evidence-freshness rules
- Integration setup — KYC/OCR, iGPR or the regional equivalent, PAS, e-signature, and the AUW engine
- Phased pilot delivery: Phase 1 Assist-first (requirement orchestration, evidence summarization, decision-packet drafting) → Phase 2 Recommend (guideline reasoning, rating recommendation) → Phase 3 Governed auto-band (a defined low-risk referral band resolves straight-through, exceptions always escalate)
- Baseline capture and pilot-scorecard reporting against agreed outcome and guardrail metrics
- Underwriting team training, including the DRUID Academy technical track for in-house enablement
- Ongoing support and managed-service options
Found in Solutions (0)
This agent is not part of any published solutions.